Financing a Backyard Remodel in South Florida: Wisetack vs Wells Fargo vs HELOC
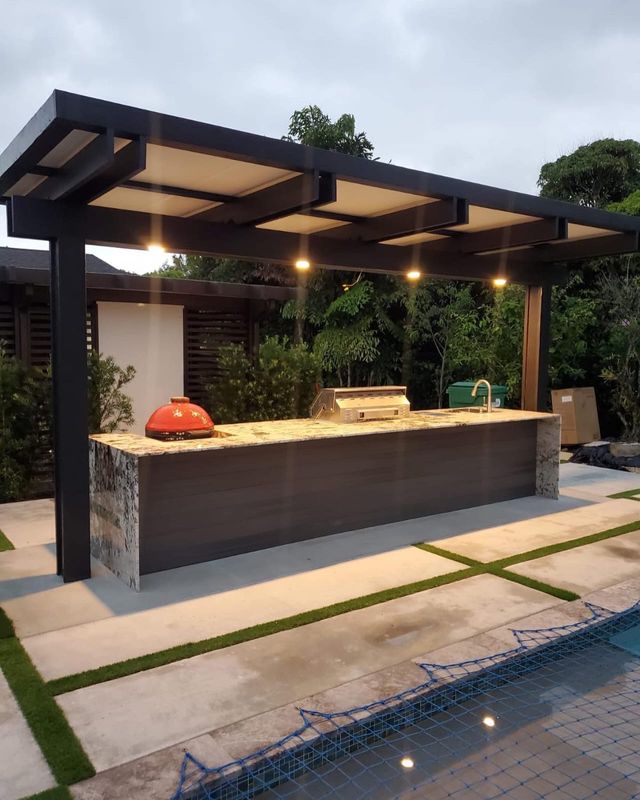
You’ve designed the backyard.
Pergola. Outdoor kitchen. New patio. Maybe artificial turf around the pool.
Then the estimate comes back at $25,000, $40,000, or more — and the conversation changes from “What should we build?” to “What’s the smartest way to pay for it?”
For homeowners across Miami-Dade and Broward, paying the entire project in cash isn’t always the best choice. Some families would rather preserve savings, spread the project over monthly payments, or take advantage of a promotional 0% APR offer when available.
Three options come up frequently:
Wisetack, Wells Fargo, and a home equity line of credit — or HELOC.
They are not the same product, and the cheapest monthly payment isn't automatically the best financing choice.
At Concrete Designs LLC, we’ve spent 20+ years building outdoor living projects across South Florida. We offer financing options through Wisetack and Wells Fargo for qualified customers, but we also believe homeowners should understand the alternatives before signing anything.
Here's how the three compare in 2026.
Wisetack vs Wells Fargo vs HELOC: Quick Comparison
| Feature | Wisetack | Wells Fargo | HELOC |
|---|---|---|---|
| Best for | Contractor project financing | Fixed-payment financing | Larger/flexible projects |
| Collateral | Generally unsecured | Depends on product | Your home |
| Check options without credit impact | Yes, per Wisetack | Wells Fargo currently offers rate checking without credit-score impact on its personal loans | Depends on lender |
| Rate structure | Fixed/simple-interest offers; some 0% APR options | Depends on financing program | Usually variable |
| 0% APR possible | Yes, for qualifying offers | Promotional contractor programs may be available; terms vary | Typically no |
| Application speed | Often very fast | Varies by program | Usually more involved |
| Home at risk | No home collateral under Wisetack consumer financing | Depends on product | Yes |
| Good for phased projects | Less flexible than revolving credit | Depends on product | Yes |
Financing is subject to approval, and terms change. Always review the actual agreement you're offered rather than choosing based on advertised rates alone.
Option #1: Wisetack Financing
Wisetack is designed specifically to let customers finance services through participating businesses.
That makes it very different from going to a bank and opening a traditional loan.
For a homeowner working with Concrete Designs, the process can be relatively simple.
Wisetack says customers can check available options without affecting their credit score, with financing currently ranging from $500 to $65,000 and terms from 3 to 120 months for qualifying programs. APR offers currently range from 0% to 35.9%, depending on creditworthiness, amount, merchant, and lending partner.
Why Homeowners Like Wisetack
The big advantages are simplicity and speed.
Instead of applying for financing before you even know what the project costs, the financing can connect directly to the contractor's proposal.
Wisetack also says:
- Checking eligibility doesn't affect your credit score
- No origination fees
- No prepayment penalties
- Simple rather than compounding interest
- Customers see repayment terms upfront
And yes, 0% APR options exist for qualifying customers and participating programs.
Wisetack currently advertises true 0% APR programs reaching as long as 24 months for participating merchants, although not every applicant, merchant, transaction, or lending partner receives those offers.
That's an important distinction.
“Financing available” does not mean everyone automatically receives 0%.
What Does 0% APR Actually Mean?
This is where homeowners need to read carefully.
A true 0% APR loan means you're not paying interest during that financing term.
For example, purely as simple math:
A $24,000 project financed for 24 months at true 0% APR would equal approximately:
$1,000 per month.
A $36,000 project over 24 months at 0% would be:
$1,500 per month.
No interest changes the total amount paid — but it doesn't necessarily mean a low monthly payment.
That's why a homeowner might have to choose between:
Shorter term + no interest
or
Longer term + interest + lower monthly payment.
Wisetack specifically distinguishes its true 0% APR offers from deferred-interest financing, where retroactive interest can sometimes become due if the balance isn't paid within the promotional period.
“Don't just ask whether it's 0%. Ask what the payment is, how long the term lasts, and what the total amount you'll repay is.”
That's the number that matters.
Option #2: Wells Fargo Financing
Wells Fargo can provide another path for homeowners who want predictable monthly payments.
The exact financing available through a contractor can depend on the specific program and promotion, so homeowners should review the financing disclosure they receive rather than assuming every Wells Fargo option carries the same terms.
Separately, Wells Fargo's publicly advertised home-improvement personal loans currently offer:
- $3,000-$100,000
- 12-84 month terms
- Fixed rates
- No origination fee
- No closing fee
- No prepayment penalty
Its published personal-loan APR range was 6.74%-26.74% as of April 2, 2026, with the lowest rate requiring qualifying circumstances and excellent credit. Rates are subject to change.
Why Fixed Payments Matter
For homeowners who don't qualify for a 0% promotion or need longer repayment periods, a fixed-rate product can provide predictability.
You know:
- Monthly payment
- Rate
- Repayment period
That makes budgeting easier.
For a large outdoor project, predictability can matter more than chasing the absolute lowest advertised rate.
Wisetack vs Wells Fargo: What's the Difference?
For a homeowner trying to keep things simple, think about it this way:
Wisetack
Strong choice when you want:
- Financing built directly into the contractor process
- Quick eligibility checking
- Potential 0% APR options
- Multiple term choices
- No home used as collateral
Wells Fargo
May make sense when you want:
- Another established financing option
- Potentially longer or different payment structures
- A fixed-payment structure depending on the product
- Larger financing capacity depending on approval and program
Concrete Designs offers access to both because one financing structure isn't ideal for every homeowner.
Option #3: Using a HELOC
A Home Equity Line of Credit, or HELOC, is completely different.
Instead of financing through the contractor, you're borrowing against the equity in your home.
The Consumer Financial Protection Bureau describes a HELOC as an open-ended line of credit that allows homeowners to repeatedly borrow against available home equity during a draw period.
Imagine your lender approves a $100,000 HELOC.
You could potentially use:
- $30,000 for the backyard
- $10,000 later for windows
- Another amount later for another renovation
As you repay borrowed amounts, available credit may replenish during the draw period, depending on the loan terms.
That flexibility is one of a HELOC's biggest advantages.
Why a HELOC Can Make Sense for a Large Backyard Remodel
Suppose you're planning:
- New patio
- Pergola
- Outdoor kitchen
- Artificial turf
- Landscaping
- Pool upgrades
Instead of financing each contractor separately, a HELOC could provide one larger credit line that you draw from as different stages are completed.
That can make sense for larger, multi-phase renovations.
It may also be useful when you're renovating other areas of the house at the same time.
The Big HELOC Risk Homeowners Need to Understand
A HELOC uses your house as collateral.
That's the part homeowners should never gloss over.
The CFPB warns that if borrowers cannot make their required payments, they could ultimately lose the home securing the debt.
That's fundamentally different from unsecured contractor financing.
HELOCs also typically have variable interest rates, meaning your payment can move as rates change. After the draw period ends and repayment begins, monthly payments may increase significantly.
So while a HELOC can provide flexibility and potentially attractive borrowing costs, you're accepting:
- Variable-rate risk
- Your property as collateral
- A more involved lending process
- Potential lender fees
- Possible payment changes later
When Wisetack May Make More Sense
Wisetack may be worth considering when:
- You're financing one defined project
- You want a fast application process
- You don't want to borrow against your home
- You qualify for an attractive APR
- You qualify for 0% APR
- You want straightforward monthly payments
For a $15,000-$40,000 backyard project, that simplicity can be attractive.
Especially when the homeowner already knows the project scope and contractor.
When Wells Fargo May Make More Sense
A Wells Fargo option may be worth comparing when:
- You want another fixed-payment alternative
- You need a different financing amount or term
- Your credit profile qualifies you for favorable terms
- You prefer financing through a major bank
Don't compare based purely on the lender's name.
Compare the actual offer:
APR + fees + term + monthly payment + total repayment.
When a HELOC May Make More Sense
A HELOC becomes more interesting when:
- The renovation is large
- You're doing multiple home projects
- You need flexibility to draw funds over time
- You have substantial home equity
- You're comfortable pledging the home as collateral
- You've compared the variable-rate risk against other financing options
For example, somebody completing a $100,000 renovation involving a pool, kitchen, landscaping, and backyard may have a completely different financing strategy from somebody installing a $12,000 pergola.
Don't Finance a $40K Project Like It's a $4K Purchase
This sounds obvious, but it's important.
A backyard remodel is not a new television.
Before financing, look at the entire project.
Let's say you're considering:
- $10,000 patio
- $12,000 pergola
- $25,000 outdoor kitchen
- $8,000 turf and landscaping
Suddenly you're looking at approximately $55,000 of work.
Instead of asking:
“What's the monthly payment?”
Ask:
- What's the total financed?
- What's the APR?
- What's the total interest?
- How many months am I paying?
- Are there fees?
- Can I pay it off early?
- Is my house securing the debt?
- What happens if rates change?
That gives you the real picture.
Cash vs Financing: Should You Finance If You Can Pay Cash?
Sometimes.
Having the cash doesn't automatically mean writing a $40,000 check is the smartest financial decision.
A homeowner may prefer to keep cash available for:
- Emergency reserves
- Investments
- Business needs
- Other renovations
- Unexpected home repairs
If you qualify for true 0% financing, preserving cash can be attractive.
On the other hand, taking a high-interest loan just to avoid using money sitting in cash may not make financial sense.
There's no universal answer.
Your personal cash reserves, income, interest rate, other debt, and risk tolerance matter.
What About Financing the Entire Backyard at Once?
This is something worth thinking about before building in phases.
Suppose your long-term plan includes:
- Patio
- Pergola
- Outdoor kitchen
- Turf
Building one piece this year and another next year can sometimes mean:
- Repeated mobilization
- Cutting completed surfaces later
- Reworking electrical
- Running utilities twice
- Designs that don't line up
If financing makes the full project comfortably affordable, completing everything together can sometimes create a better result.
But financing shouldn't be used as an excuse to build beyond what you can responsibly afford.
“I'd rather build the right $25,000 backyard than talk somebody into a $60,000 project they're going to regret paying for.”
Five Things to Compare Before Choosing Financing
Don't compare only monthly payments.
1. APR
How much is the money actually costing you?
2. Total Repayment
A low monthly payment stretched over many years can cost considerably more overall.
3. Term
How long will you still be paying for the project?
4. Fees
Look for:
- Origination fees
- Closing costs
- Annual fees
- Early payoff charges
5. Collateral
This is a huge one.
Understand whether the loan is unsecured or whether you're pledging your home.
Which Financing Option Would We Choose?
There's no single winner.
For a Qualified Homeowner Getting True 0% APR
We'd look very closely at that option first.
It's difficult to beat financing that doesn't charge interest, assuming the monthly payment comfortably fits the budget and the terms are truly 0%.
For a Larger Project Needing More Time
Compare Wells Fargo and other fixed-rate options against the HELOC's available rate and terms.
For a Multi-Stage Whole-Home Renovation
A HELOC may offer useful flexibility — but the homeowner needs to be comfortable with variable rates and putting the house behind the loan.
The right answer comes down to the actual offers you qualify for, not the advertisements.
The Project Still Matters More Than the Financing
Financing can make a backyard remodel more manageable.
It can't make a bad project good.
Whether you're paying cash, using Wisetack, financing through Wells Fargo, or drawing from a HELOC, you still need to look at:
- Contractor licensing
- Permits
- Materials
- Drainage
- Engineering
- Scope
- Itemized pricing
Don't let the monthly payment distract you from the total project.
A contractor saying:
“It's only $499 per month.”
without telling you how many months you're paying or what the APR is isn't giving you the whole story.
We'd rather know than wonder.
At Concrete Designs, we'll show you the project price first. Financing is simply a way to pay for it — not a reason to inflate what you build.
Family-owned · 20+ years · Miami-Dade & Broward.
FAQs
Does Concrete Designs offer 0% APR financing?
Concrete Designs offers financing through Wisetack and Wells Fargo. Wisetack currently offers qualifying 0% APR options through participating programs, but approval and terms depend on the borrower, transaction, merchant program, and lending partner.
Does checking Wisetack financing hurt your credit?
Wisetack states that checking eligibility does not affect your credit score.
Is a HELOC better than contractor financing?
Not automatically. A HELOC can provide flexible borrowing and may be useful for large, multi-stage renovations, but it typically carries a variable rate and is secured by your home. Contractor financing may be simpler for one defined project.
Can I pay Wisetack financing off early?
Yes. Wisetack says its financing carries no prepayment penalty.
Is a HELOC risky?
A HELOC uses your home as collateral. If you cannot make the required payments, foreclosure is possible. Its rate is also usually variable, meaning payments can change.
Ready to get started? Get a free on-site estimate from the Concrete Designs team — we'll walk your property, talk through what's possible, and send you a fixed-price quote with no surprises. Call (786) 269-9215, or message us at concretedesignsllc.com. Ask about 0% APR financing through Wisetack and Wells Fargo. Family-owned · 20+ years · Miami-Dade & Broward.